HDB Income Ceiling 2026: The New $16,000 Limit, the Fine Print HDB Just Confirmed, and the Trap Nobody Is Talking About
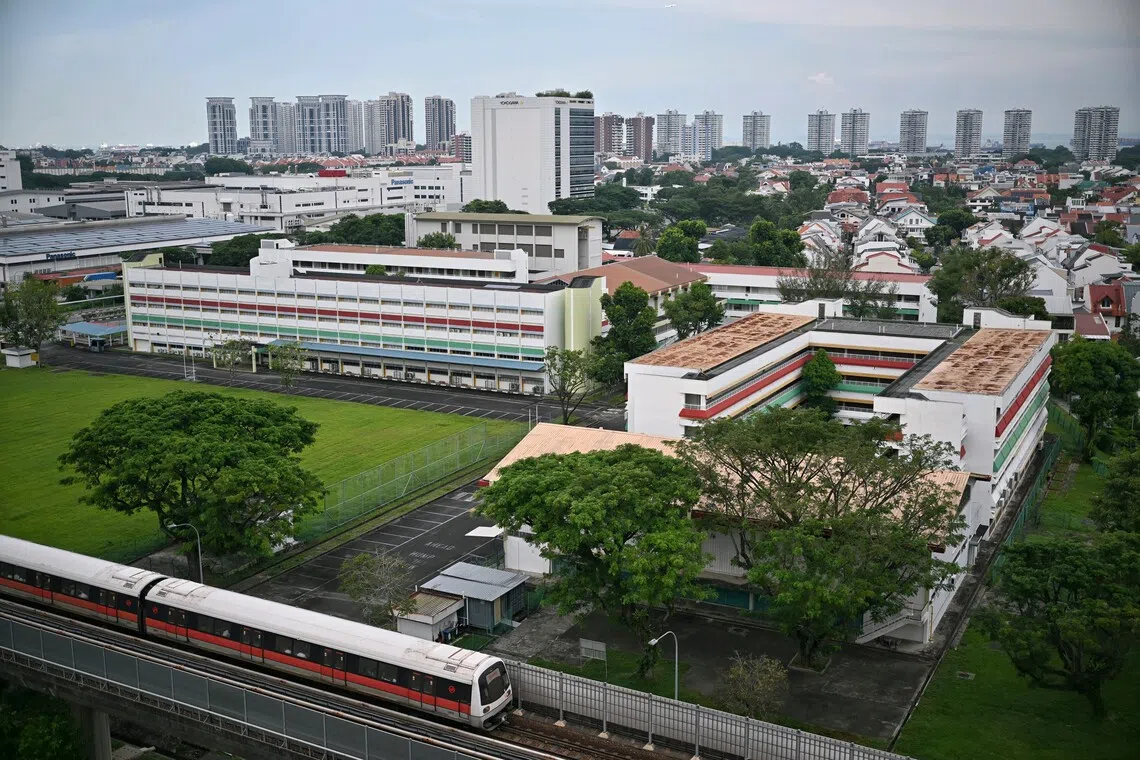
The HDB income ceiling just made its biggest jump since 2019. From 24 August 2026, families earning up to $16,000 a month can buy a new BTO flat — up from $14,000 — and the EC ceiling moves from $16,000 to $18,000. Singles get a bump from $7,000 to $8,000. PM Wong announced it at the National Day Rally on 23 August, it took effect the very next morning, and HDB has now published the implementation details that decide who actually benefits.
I’ve been helping buyers navigate these ceilings for 17+ years, and here’s what I’ll tell you upfront: the headline numbers are the easy part. The fine print — which ceiling applies to your HFE letter, why the new EC ceiling is mostly a 2027 story, and what this does to resale demand between now and November — is where the money is. Let’s go through all of it.
- What Changed: Every New HDB Income Ceiling Number
- The Fine Print HDB Just Confirmed
- The Date That Actually Matters: 25 September
- The EC Tender-Date Trap
- What $16,000 Actually Buys You: The Loan Math
- Three Households, Three Very Different Outcomes
- Extra Ballot Chances: The Feb 2027 Queue Math
- Who Wins, Who Loses
- Sellers: Your 60–90 Day Window
- My Verdict
- HDB Income Ceiling FAQ
What Changed: Every New HDB Income Ceiling Number
Here is the full table — not just the two numbers the headlines carried. All changes took effect 24 August 2026 and apply to households that apply for an HFE letter from that date.
| Scheme | Old ceiling | New ceiling | Notes |
|---|---|---|---|
| New BTO flats (families) | $14,000 | $16,000 | Includes 2-room Flexi on short lease |
| Singles aged 35+ (new flats) | $7,000 | $8,000 | 2-room Flexi BTO |
| New Executive Condominiums | $16,000 | $18,000 | ⚠️ Only ECs from land tenders closing on/after 24 Aug 2026 — see the trap below |
| Resale flats with CPF housing grants | $14,000 | $16,000 | Resale itself still has NO income ceiling — this is for grant eligibility |
| HDB housing loan | $14,000 | $16,000 | Confirmed aligned in the implementation release |
| Extended/multi-generation families | $21,000 | $24,000* | *Reported in implementation coverage; each family nucleus capped at $16,000 |
| Lease Buyback Scheme | $14,000 | $16,000* | *Seniors monetising their flat |
| Community Care Apartments | $7,000 | $8,000* | *First age-55 CCAs launch in the November BTO |
For context: the family ceiling was $8,000 as recently as 2011, went to $10,000 that year, $12,000 in 2015, $14,000 in 2019 — and now $16,000 in 2026. Roughly once every four to five years, the government catches the ceiling up to wage growth. This round was arguably overdue: seven years is the longest gap between raises since the early 2010s.
The Fine Print HDB Just Confirmed
The Rally speech gave us headlines. The implementation release — you can read HDB’s official announcement for the full text — settled the four questions I’d been fielding all week from clients:
1. The HDB loan ceiling follows to $16,000 — confirmed
This matters more than the BTO ceiling itself for many families. A household at $15,000 could previously buy a resale flat (no ceiling on the purchase) but had to take a bank loan. Now they qualify for an HDB concessionary loan: 75% LTV instead of bank-package terms, no lock-in, no cash penalty to redeem early, and the 2.6% rate — which, yes, is above bank fixed rates right now, but comes with flexibility banks won’t give you. My take on that trade-off is in my HDB loan vs bank loan guide [DRAFT — swap link when live].
2. Resale grant eligibility follows to $16,000 — confirmed
A first-timer family at $15,500 buying resale was previously grant-locked-out. From 24 August they’re inside the CPF Housing Grant net for resale purchases (up to $80,000 for a family buying 4-room or smaller, before proximity top-ups). That’s real money appearing in the resale market’s demand pool — remember this when we get to the seller section.
3. The Enhanced CPF Housing Grant is NOT changing — confirmed
The EHG income ceiling stays at $9,000 average household income, with the maximum $120,000 grant still reserved for the lowest bands. So the new $14,000–$16,000 entrants get eligibility, not subsidies. They can ballot; they won’t collect EHG. That’s a deliberate design: the government widened the door without widening the wallet.
4. The ceiling that applies is the one on your HFE letter date
The revised ceilings apply to households applying for an HFE letter from 24 August 2026. If you had a pending HFE application lodged before that date and the old ceiling disqualified you, HDB’s guidance is to cancel and resubmit. If you hold a valid HFE letter issued under the old rules and you’re now newly eligible for more, same answer — reapply. My step-by-step HFE guide is here: how to apply for your HFE letter.
The Date That Actually Matters: 25 September
The October BTO exercise has been pushed to November 2026 — about 7,960 flats across Bedok (including the Bayshore debut), Toa Payoh, Geylang, Sembawang, Tengah and Yishun — precisely so that newly eligible households have time to get their paperwork in.
But here’s the deadline buried in the coverage: to ballot in the November exercise, you need your HFE application (with complete documents) in by 25 September 2026. HFE processing is not instant — it can take up to 21 days, longer in a surge, and I promise you there will be a surge. Every $14,001–$16,000 household in Singapore just became a potential BTO applicant on the same day.
If you’re in that band and Bayshore or Toa Payoh is on your list: start the HFE application this week. Gather your latest payslips, NOA, and CPF statements now. The comparison of what you’re actually balloting for — Standard, Plus or Prime — is in my Plus/Prime/Standard breakdown [DRAFT — swap link when live].
The EC Tender-Date Trap
This is the part I’ve seen almost nobody explain properly, and it’s the difference between a household planning 2026 and a household planning 2028.
The $18,000 EC ceiling only applies to new units in ECs whose land tender closes on or after 24 August 2026. Every EC currently selling — and every EC that launches from land already tendered — keeps the $16,000 ceiling. Balance units at existing projects: still $16,000.
Walk the timeline with me. A site tendered after 24 August gets awarded, planned, and launched typically 12–15 months later. That puts the first $18,000-eligible EC launches at late 2027, realistically 2028. If your household earns $16,001–$18,000 today, the Rally headline sounded like your door just opened. It did — but the door is at the end of a very long corridor.
Why does the ceiling exist at all? Because EC demand at the margin is intense: income-ceiling waiver appeals nearly tripled from 461 in 2024 to 1,147 in 2025, and only about a third of appeals (845 of 2,583) were granted across 2020–2025. Those 1,147 households are exactly who this change is for — in two years’ time.
What a $17k household can do now instead:
| Option | Ceiling? | Timing | My take |
|---|---|---|---|
| Resale EC (past 5-year MOP) | None | Now | The genuine “now” option — privatised or privatising stock, no income cap, no ballot |
| Resale HDB (no grants) | None on purchase | Now | Grants now reach you at $16k; above that, purchase is still open |
| New EC at $18k ceiling | $18,000 | ~Late 2027–2028 | Worth waiting only if your timeline is genuinely flexible |
| Entry-level private condo | None | Now | OCR launches from ~$1.6m — check the affordability math first |
I wrote about why ECs at the ceiling margin are such ferociously good value in my Altura EC piece — the logic has only strengthened. The full 2026 EC landscape, including the 8 May rule reset, is in my executive condo guide [DRAFT — swap link when live].
What $16,000 Actually Buys You: The Loan Math
Eligibility is one thing. Servicing is another. The Mortgage Servicing Ratio caps your monthly HDB/EC repayment at 30% of gross income, computed at a stress rate — 3% floor for HDB loans, 4% for bank loans. Here’s what the new ceilings translate to. (My assumptions: 25-year tenure for HDB flats, 30-year for EC bank loans, stress floors as above. Run your own numbers with the free calculators at listings.sg/tools.)
| Household | MSR budget (30%) | Max loan (stressed) | Indicative max price @75% LTV |
|---|---|---|---|
| $14,000 (old BTO ceiling) | $4,200/mth | ~$886k (3%, 25yr) | ~$1.18m |
| $16,000 (new BTO ceiling) | $4,800/mth | ~$1.01m (3%, 25yr) | ~$1.35m |
| $16,000 (old EC ceiling, bank loan) | $4,800/mth | ~$1.01m (4%, 30yr) | ~$1.34m |
| $18,000 (new EC ceiling, bank loan) | $5,400/mth | ~$1.13m (4%, 30yr) | ~$1.51m |
Read that middle column carefully. The move from $14k to $16k adds roughly $125,000 of stressed borrowing capacity for an HDB-loan buyer. That comfortably covers the gap between a Standard-tier BTO and the Plus-tier flats in the November exercise — or between a $750k and an $870k resale flat. In practice, almost no BTO flat outside Prime pushes a $16k household anywhere near its MSR limit; the constraint bites on resale and EC purchases, not new flats. These are planning figures, not a bible — your actual approval depends on tenure, age, debts and the TDSR overlay, which I break down in TDSR vs MSR.
Three Households, Three Very Different Outcomes
Profile 1: The $15,500 couple — the big unlock
Two professionals, combined $15,500, previously $1,500 over the BTO line. Before 24 August their options were resale without grants (bank loan only) or an EC. Today they can: ballot for the November BTO including Bayshore’s debut, take an HDB loan, or buy resale with first-timer grants. This is the single biggest winner category — and if that’s you, the 25 September HFE deadline is your entire to-do list this month. Whether BTO or resale actually suits you better is a different question — my framework is in HDB BTO vs resale flats.
Profile 2: The $17,200 family — the waiting room
Over the old EC ceiling, under the new one. The Rally sounded like their moment; the tender-date fine print says their first eligible new EC launches around late 2027. Their real choice is: wait 18+ months while saving harder, or pivot to a resale EC or entry-level private now. At $17,200, the income needed for a ~$1.5m condo is within reach on the numbers [DRAFT — swap /income-needed-to-buy-condo-singapore when live] — the question is whether the new-EC discount to private is worth the wait. For most families I advise with school-age kids and a lease running out, it isn’t. For a young couple renting cheaply with parents? Different answer.
Profile 3: The Toa Payoh seller — the demand wave
Owns a 4-room in the resale sweet spot ($700k–$900k). Since 28 July, private downgraders no longer wait 15 months to buy resale. Since 24 August, every $14k–$16k first-timer family can now buy her flat with grants. Two demand taps opened within a month, while the November BTO — her main competition for buyers — won’t produce keys for years. If she’s been waiting for a strong tape to list into, this is it. More on timing below.
Extra Ballot Chances: The Feb 2027 Queue Math
The second Rally announcement got less airtime but changes BTO odds materially: from the February 2027 exercise, first-timer families get one additional ballot chance per Singapore Citizen child aged 18 and below (including one on the way).
Quick queue math. First-timer families already receive two ballot chances. A family with two young kids will hold four chances from February — double their current weight, and four times a second-timer’s single chance. Childless first-timer couples keep two chances but now compete against heavier-weighted families in the same pool, on top of the newly admitted $14k–$16k households.
Two strategic reads. First: if you’re a first-timer without children, the November 2026 exercise is relatively kinder to you than February 2027 onwards will be — one more reason not to miss the 25 September deadline. Second: if you’re expecting a child in early 2027, the calculus flips — waiting one exercise buys you an extra chance. HDB will publish the precise mechanics closer to the February exercise; treat the arithmetic above as directionally right, not gospel.
Who Wins, Who Loses
| Household | Before 24 Aug | After 24 Aug | Verdict |
|---|---|---|---|
| Family $14,001–$16,000 | Resale (no grants) or EC only | BTO + HDB loan + resale grants | Biggest winner |
| Single 35+, $7,001–$8,000 | Resale only, no grants | 2-room Flexi BTO + grants | Winner |
| Family $16,001–$18,000 | Private/resale only | New ECs — from ~late 2027 tenders | Winner on paper, waiter in practice |
| Family with 2–3 kids, first-timer | 2 ballot chances | 4–5 chances from Feb 2027 | Winner |
| Childless first-timer couple | 2 chances in today’s pool | 2 chances in a bigger, heavier pool | Relative loser — apply in November |
| Family above $18,000 | Private/resale only | Unchanged — the cliff just moved up | No change |
| Resale sellers (mass-market) | Soft tape, two down quarters | Grant-armed buyers added to the pool | Quiet winner |
| Current EC developers/buyers at $16k cap | — | Balance units keep the old ceiling | Neutral — no retroactive widening |
Sellers: Your 60–90 Day Window
Let me put my seller hat on, because this is where I think the market is genuinely mispriced on information.
The HDB Resale Price Index has printed two straight negative quarters (−0.1% Q1, −0.3% Q2) — the first such stretch since 2020 — largely on the back of a heavy MOP supply wave. Sentiment among sellers I meet is cautious. But look at what just happened to the demand side inside four weeks: the 15-month wait-out for private downgraders was removed on 28 July, and now every household up to $16,000 buys resale with grants and an HDB loan. Analysts across the big agencies expect the ceiling raise to feed resale demand precisely because the BTO route, while newly open, still means a 3–4 year wait — and ERA’s own house view is that resale prices firm up on this.
Meanwhile the November BTO will absorb some buyer attention — 7,960 flats’ worth — but those are paper flats. A family that needs keys in 2026–27 is your buyer, not HDB’s.
So if you’re a mass-market seller — especially 4-room and 5-room in the $650k–$950k band where the $14k–$16k cohort shops — the window between now and the November exercise is unusually favourable: maximum new demand, minimum new competition. Get the pricing right (that’s the part sellers fumble — see my HDB resale prices 2026 analysis and the timing playbook [DRAFT — swap /best-time-to-sell-hdb when live]), list clean, and let the grant-armed first-timers compete. Or start with a free valuation at buycondo.sg — we’ll tell you honestly if your flat isn’t the type this wave lifts.
🎯 My Verdict
This is the most consequential HDB eligibility change since 2019, and its effects land in a specific order: resale demand first (immediately — grants + loans for the $14k–$16k cohort), BTO application rates second (November), EC demand last (late 2027 when the first $18k-eligible sites launch).
If you earn $14k–$16k: your HFE application is due 25 September for the November ballot. Move this week.
If you earn $16k–$18k: ignore the headline; your new-EC door opens in ~2027. Decide between resale EC now and waiting — don’t drift.
If you’re selling a mass-market resale flat: two demand taps just opened and your competition is paper flats. The next 60–90 days are the strongest listing window this year.
新加坡买房,就找对的团队 — We Serve with Heart.
HDB Income Ceiling FAQ
What is the HDB income ceiling in 2026?
From 24 August 2026: $16,000 gross monthly household income for new BTO flats (families), $8,000 for singles aged 35+, and $18,000 for new Executive Condominiums from land tenders closing on or after 24 August 2026. Resale flats have no income ceiling on the purchase itself; $16,000 is the ceiling for CPF housing grants and HDB loans.
Does the new $16,000 ceiling apply to resale flats?
You could always buy a resale flat at any income. What changed: households up to $16,000 (previously $14,000) now qualify for CPF housing grants and the HDB concessionary loan on a resale purchase.
I earn $17,000 — can I buy an EC now?
Not the ones currently selling. The $18,000 ceiling only covers ECs from land tenders closing on/after 24 August 2026, which won’t launch until around late 2027. Existing EC projects and their balance units keep the $16,000 cap. Your “now” options are resale ECs (no ceiling), resale HDB, or private.
My HFE letter was issued before 24 August under the old ceiling. What do I do?
If the new ceilings change your eligibility, cancel and reapply — the ceiling that applies is based on when you apply for your HFE letter, and letters issued under the old rules don’t auto-upgrade. For the November BTO, complete applications are due by 25 September 2026.
Did the Enhanced CPF Housing Grant change too?
No. EHG bands are unchanged — the ceiling stays at $9,000 average household income with grants up to $120,000 tiered below that. Newly eligible $14k–$16k households get access to BTO, HDB loans and the ordinary CPF housing grants, but not EHG.
How do the extra ballot chances work?
From the February 2027 exercise, first-timer families receive one extra ballot chance per Singapore Citizen child aged 18 or below, on top of their existing first-timer chances. A first-timer family with two kids effectively doubles its current ballot weight. Exact mechanics will be published by HDB nearer the exercise.
Why was the October BTO moved to November?
To give newly eligible households time to apply for HFE letters under the revised ceilings. The exercise offers roughly 7,960 flats across Bedok/Bayshore, Toa Payoh, Geylang, Sembawang, Tengah and Yishun, plus the first age-55 Community Care Apartments.
Is the income ceiling raise going to push up resale prices?
Directionally, yes — it adds grant-armed buyers to a market that just absorbed two soft quarters, on top of the July removal of the 15-month wait-out. Most analysts expect a firmer second half. Magnitude is the honest unknown; watch the Q3 flash estimate on 1 October.
In the $14k–$18k band and not sure which door to walk through — BTO, resale, EC or private?
📱 WhatsApp me directly: 8986 1688
Or browse my video breakdowns at buyers.sg
Disclaimer: This article is for general information only and does not constitute financial advice. Policy parameters are as announced by HDB effective 24 August 2026 and accurate as of 27 August 2026; scheme details may be refined by HDB — always verify against official sources before committing. Loan figures are indicative planning estimates based on stated assumptions, not a credit approval. Gary Lim is a licensed real estate salesperson (CEA Reg. No. R009877B) with ERA Realty Network Pte Ltd (Licence No. L3002382K).